Featured Research
Macroeconomic Insights: Lula’s New Term Set to Begin as Inflation Nears Its Peak
Brazil re-elected President Luiz Inácio Lula da Silva on 25 October, with 51.79% of valid votes against 48.21% for Flávio Bolsonaro. Financial markets reacted sharply the following day. The dollar rose 8.36% against the real to R$5.406, its largest daily gain in 23...
Macroeconomic Insights: Lula’s New Term Set to Begin as Inflation Nears Its Peak
Brazil re-elected President Luiz Inácio Lula da Silva on 25 October, with 51.79% of valid votes against 48.21% for Flávio Bolsonaro. Financial markets reacted sharply the following day. The dollar rose 8.36% against the real to R$5.406, its largest daily gain in 23 years, while the Ibovespa fell 13.88% and the January 2028 DI futures yield rose 194 basis points to 14.8%.
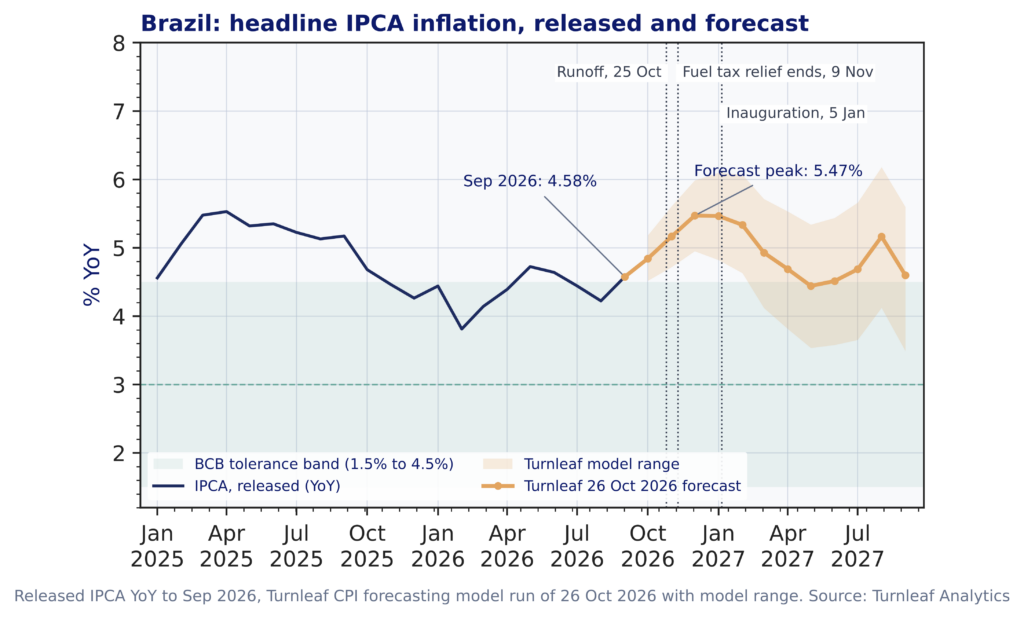
Campaign-period measures are expected to lower month-on-month inflation in October temporarily, but our forecast points to renewed upward pressure by year-end. In the final weeks before the election, the government eliminated federal taxes on gasoline and extended a diesel subsidy, while the electricity regulator separately moved to the green tariff flag. Together with a slowdown in Turnleaf’s food tracker, these developments should restrain the October MoM print. However, the gasoline relief is scheduled to expire on 10 November, before the inauguration on 5 January 2027. As temporary relief fades and base effects turn less favourable, Turnleaf’s 26 October forecast projects headline IPCA rising from 4.58% YoY in September to 5.47% in December and January, above the central bank’s 4.5% upper tolerance limit (Figure 1). The forecast uses high-frequency data through 26 October, so it captures only the first trading day of the post-election depreciation of the real and none of the subsequent repricing of inflation expectations, which we expect to prompt upward revisions.
Figure 1. Released IPCA YoY to September 2026, Turnleaf’s 26 October 2026 forecast with model range and the election calendar.
 High-frequency indicators suggest the October relief is transitory
Turnleaf’s October nowcast stands at 0.35% MoM, 0.05 percentage points below the 0.40% implied by the model’s ten-year historical average. The four largest drivers of our latest model outcomes suggest that the factors pulling inflation lower are largely temporary, while those pushing it higher reflect more persistent pressures.
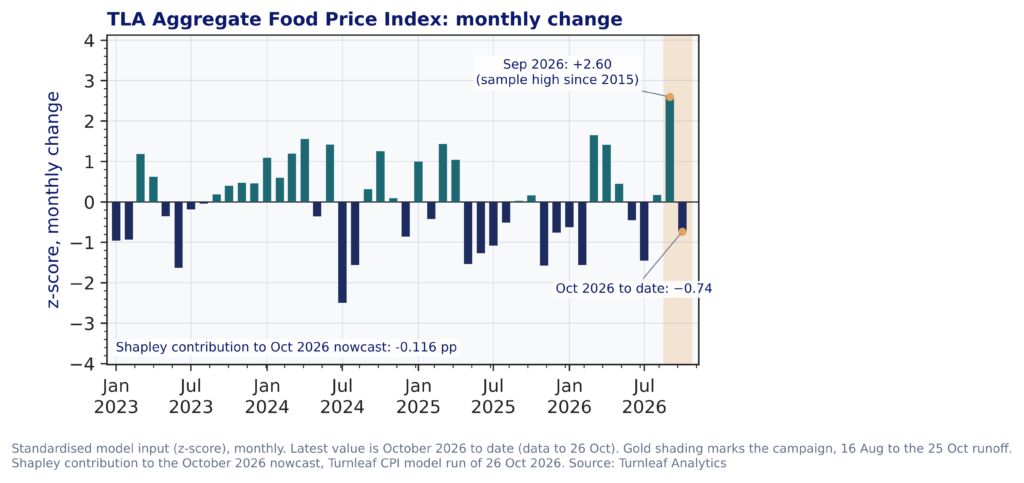
Food accounts for most of the downward contribution. Turnleaf’s proprietary high-frequency food tracker, the TLA Aggregate Food Price Index, recorded in September its strongest monthly growth relative to its own history since the sample began in 2015, and in October to date growth has fallen back below its historical average (Figure 2). Because the series is standardised, the October reading indicates below-average food price growth, not necessarily falling prices. Following an exceptional September, this is consistent with a slowdown in food inflation, with limited evidence of a sustained disinflationary trend.
Figure 2. TLA Aggregate Food Price Index, standardised monthly change, with its contribution to the October 2026 nowcast.
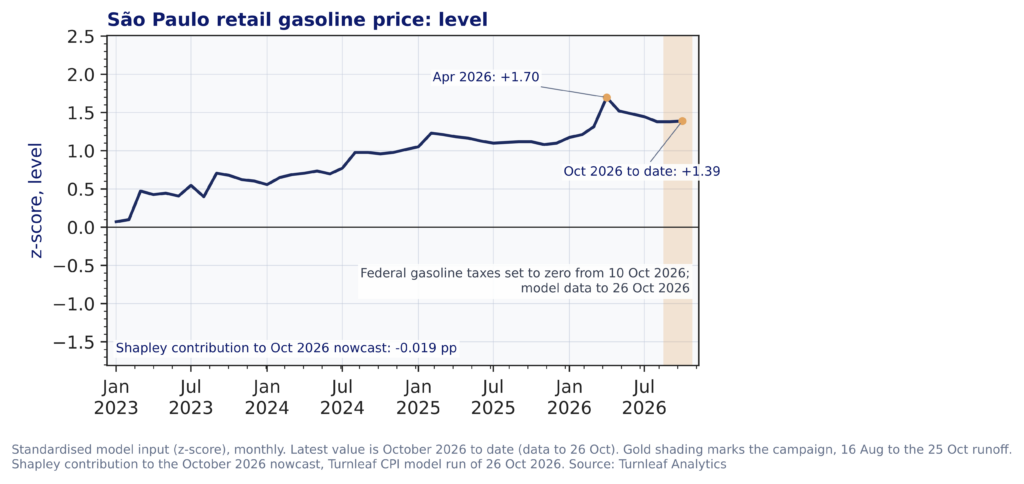
Pump prices have so far shown little response to the October gasoline tax cut. The model uses high-frequency data on a month-to-date basis, and the São Paulo retail gasoline price, the series through which fuel prices enter the model, covers October through 26 October, more than two weeks after the cut took effect. The series has eased since its April peak but was broadly unchanged in October to date relative to September (Figure 3). Decree 13.134/2026 eliminates PIS/Pasep, Cofins and Cide taxes on gasoline A from 10 October to 9 November, extending relief of R$0.63 per litre already in place to R$0.89 per litre. We estimate that the additional tax cut, together with the shift to the green electricity tariff flag, could lower October CPI by about 0.22 percentage points MoM if fully passed through, considerably more than the pump-price data show so far.
Figure 3. São Paulo retail gasoline price, standardised level, with its contribution to the October 2026 nowcast.
The expiry of fuel relief is expected to push inflation higher in November and December. When the gasoline and ethanol relief ends on 10 November, the full R$0.89 per litre of federal taxes returns, including the R$0.63 of relief that predates October, so the rebound in prices exceeds the October reduction. The R$2.12-per-litre diesel subsidy was extended on 27 October for a further 30 days, which moves most of its expiry effect from November into December. On that basis we estimate that the expiries add about 0.33 percentage points to November CPI and 0.19 points to December CPI on a MoM basis, assuming no further extensions.
Our 26 October CPI forecast was produced with information available on that date. It therefore treats the diesel subsidy as expiring on 26 October, the scheduled date at the time, and does not reflect the extension announced the following day. The extension moves about 0.05 percentage points of the expected increase from the November CPI forecast of 0.49% MoM into December, which we will incorporate in the next run.
Elevated global fuel costs reinforce the upward pressure. Jet fuel prices recorded above-normal monthly increases in eight of the first ten months of 2026, including October to date, with the largest in March (Figure 4). Alongside crude oil, this indicates that domestic tax relief is temporarily cushioning consumers from higher global fuel costs.
Figure 4. Jet fuel price, standardised monthly change, with its contribution to the October 2026 nowcast.
To read the rest, visit our latest Substack post here.
Research Archive
Macroeconomic Insights: Where Will the Oil Shock Hit Next?
Turnleaf reads the current inflation data as a test of duration. Fuel prices have lifted headline CPI, while core has stayed contained because energy prices have not remained...
Macroeconomic Insights: The Hidden Cost of the Iran War
Over the past several months, Turnleaf has examined the inflationary impact of the Iran conflict across fuel, food and airline prices, as well as the intermediary inputs that...
Macroeconomic Insights: How the Hormuz Closure is Moving Airfares
The Strait of Hormuz closure is best understood as an inflation shock transmitted through energy logistics. The relevant issue is that usable supply has become harder to move and...
Macroeconomic Insights: Food Prices Have Moved Past the Ceasefire Question
Since the onset of the March 2026 escalation in the Gulf/Iran conflict, markets have focused overwhelmingly on oil, with Brent pushing past $100 per barrel. Headlines on the war...
Macroeconomic Insights: Repricing Conflict, Inflation Next
On April 17, markets briefly priced in peace. Iran had declared the Strait of Hormuz open, a Lebanon ceasefire had just started, and WTI dropped 6% in a day. Prediction markets...
The choice decision
You always have choices. Should I order cheese in my burger? Should I choose the cheese or cream knafa? There are also additional choices, not immediately obvious from the menu....
Macroeconomic Insights: Mexico CPI— Fuel Smoothing Muting the Shock, Local Prices Still Bite
Turnleaf’s Mexico CPI nowcast for May 2026 is 4.04 percent YoY, slightly below Banxico nowcast of 4.09 percent YoY. Figure 1 shows a softer near-term profile, with the model...
Macroeconomic Insights: Where the Rice Shock Travels Next
First the Philippines, now Thailand. Who falls next? We take a closer look at how the Iran oil shock is reshaping the 12-month inflation outlook across Asia, and why rising rice...
Macroeconomic Insights: Philippines CPI — Who Is Falling First?
Philippines inflation has become a test case for how rapidly an external supply shock can propagate through a domestic food system. The April print was a material upside...
Macroeconomic Insights: Hungary CPI – Orban Out, Magyar In
Hungary’s inflation outlook over the next 12 months is increasingly shaped by a transition away from direct price controls toward a more mixed regime combining gradual...
Macroeconomic Insights: Turnleaf’s Guide to Understanding the Hormuz Shock
The shock has already landed Despite conflicting announcements about whether the Strait of Hormuz may close, vessel traffic remains underwhelming and supply concerns persist....
Macroeconomic Insights: Are Global Food Prices on Their Way Up?
Since the outbreak of the Hormuz conflict in early March 2026, media coverage has understandably centered on oil prices and their pass-through to fuel and transportation costs....
Macroeconomic Insights: Oil Prices and Inflation– Will the Ceasefire Last?
To gauge how markets are pricing the durability of the current US-Iran ceasefire, we aggregated conflict resolution probabilities across four prediction market platforms...
Macroeconomic Insights: There’s No Ceasefire for Inflation
Late last night (April 7, 2026), the U.S. and Iran agreed on a two-week ceasefire to allow for diplomacy. During this time, Iran has agreed to coordinate the passage of vessels...
Macroeconomic Insights: Hormuz Shock and the Return of Global Inflation (Expectations?)
The closure of the Strait of Hormuz following the US-Israeli strikes on Iran on 28 February 2026 has triggered the largest physical supply disruption in the history of the global...