Featured Research
Macroeconomic Insights: Hormuz, El Niño and Apparel Inflation
Commercial traffic through the Strait of Hormuz has been severely disrupted since 28 February 2026 and has not meaningfully normalised. Lloyd's List Intelligence counted just 73 transits in the week to 16 August, around 10 a day, against roughly 103 trading vessels a...
Macroeconomic Insights: Hormuz, El Niño and Apparel Inflation
Commercial traffic through the Strait of Hormuz has been severely disrupted since 28 February 2026 and has not meaningfully normalised. Lloyd’s List Intelligence counted just 73 transits in the week to 16 August, around 10 a day, against roughly 103 trading vessels a day before the conflict. Marsh reported additional war risk premiums of 7.5 to 10% of hull value on 22 July, up from 1 to 3% a few weeks earlier. Brent was $93.27 a barrel on 21 August, 37.7% above a year ago, and Dutch TTF gas was €66.52 per MWh, 98.1% higher. A second shock is building in parallel. The US Climate Prediction Center has moved to an El Niño Advisory and now puts a greater than 90% probability on a very strong event through the northern hemisphere autumn and winter. Textiles sit downstream of both. Energy prices set the cost of synthetic fibre and of moving finished garments, and El Niño is an important determinant of cotton yields and availability. Neither has yet registered in clothing and footwear inflation across the major advanced economies. We expect these costs to reach retail prices with a lag of several quarters, and our proprietary apparel index has already begun to reflect that.
Two Channels, Two Speeds
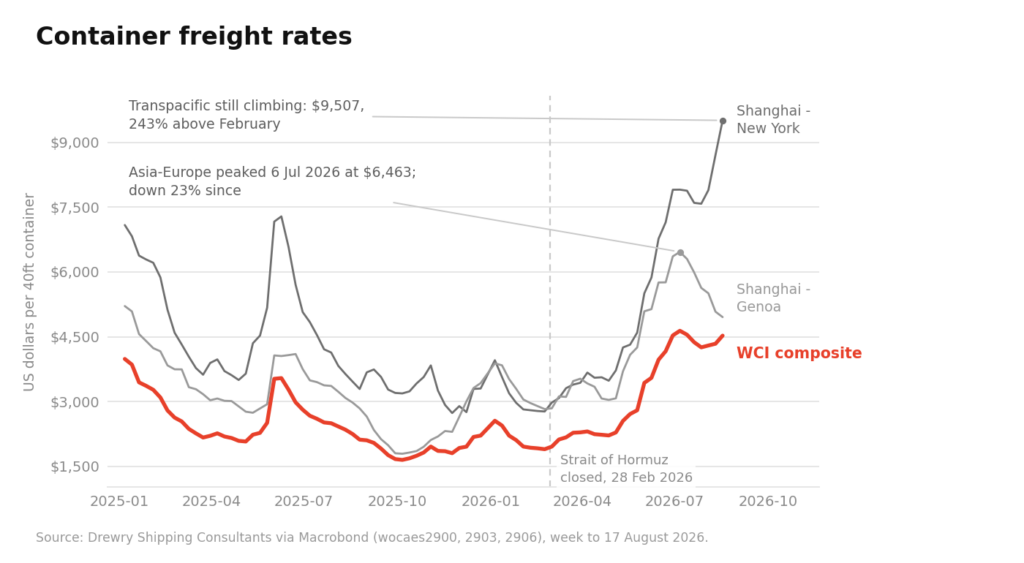
The faster channel runs through energy. Polyester is roughly 59% of world fibre supply against 19% for cotton, which makes the average garment a petrochemical product whose cost moves with crude. That cost has carried through to the fibre itself, with Asian polyester staple prices rising 12 to 15% quarter on quarter in the second quarter as paraxylene followed oil higher. Spot container freight has moved the same way. Drewry’s World Container Index, a weekly composite of eight major East-West lanes, is some 60% above its late-May level, and the move is concentrated on the transpacific, where Shanghai to New York is running at $9,507 per 40ft container, 243% above February, while Asia to Europe has fallen 23% from its July peak (Figure 1). Most apparel volume moves under annual contracts, which reprice with a lag, so today’s spot level indicates what importers will pay at the next negotiation more than what they are paying now. Rebased to January 2026, the month before the closure, European gas was 50% higher in July and Brent 30% higher, and both remain elevated.
Figure 1
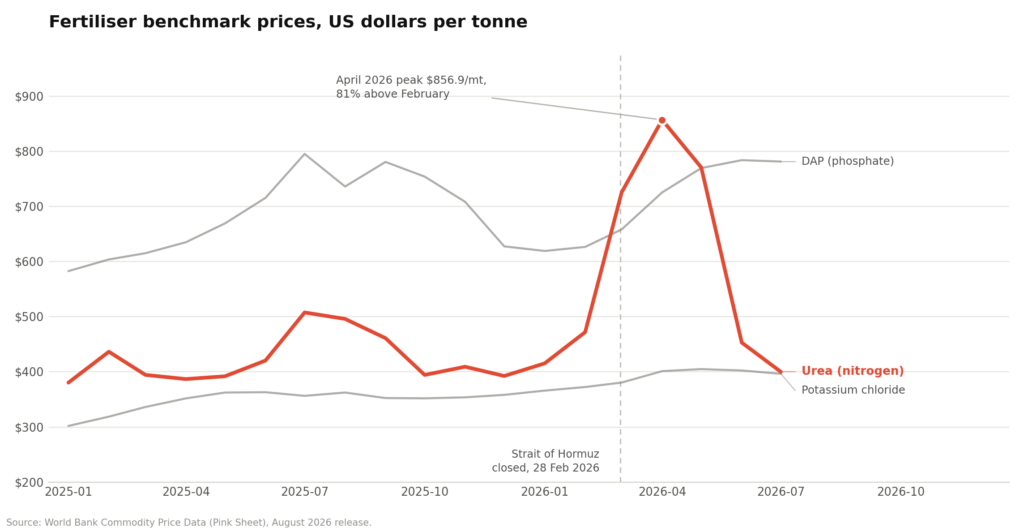
The slower channel runs through agriculture. The fertiliser shock has already peaked and largely reversed, while cotton remains under upward pressure. The Middle East accounts for nearly a quarter of global urea exports, and urea duly rose 81% between February and April before the entire move unwound over the following three months (Figure 2). Phosphates and potash barely participated, because nitrogen fertiliser is synthesised from natural gas and urea therefore traded as an energy derivative through the closure while the mined nutrients did not. Benchmark urea prices have reversed, although that relief has not reached domestic producer prices, with the US producer price index for fertiliser materials still 21% above its January level in July.
Figure 2
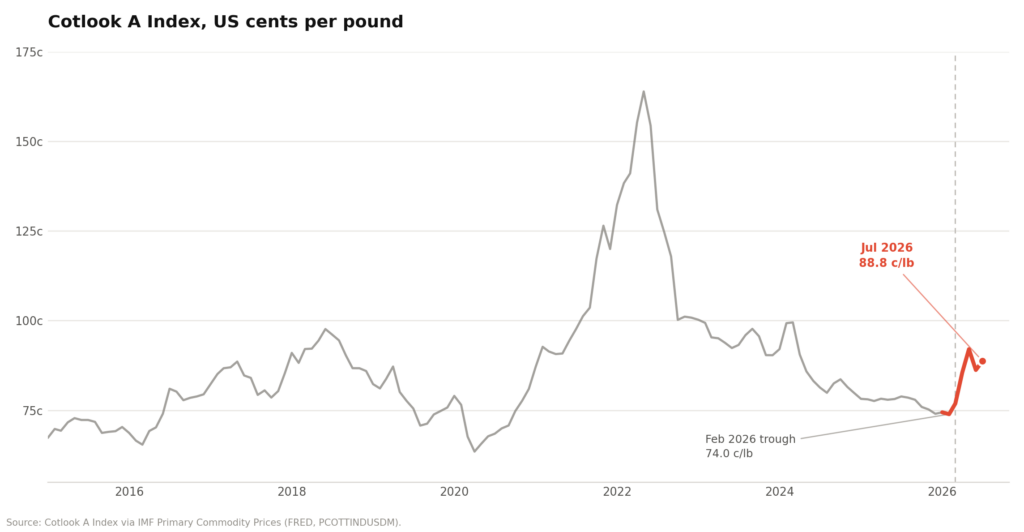
Cotton is where El Niño enters the cost base. India’s June to July monsoon delivered 87% of the long-period average, pushing cotton sowing sharply below year-ago levels before late rains narrowed the shortfall. Prices followed, with the Cotlook A Index rising from a February trough of 74.0 cents a pound to 88.8 cents in July and ICE cotton settling at 88.33 cents on 20 August, 34.2% above a year ago, which leaves the market at its highest since early 2024 (Figure 3). The tightness is structural as well as seasonal, with world ending stocks projected at their lowest since 2011/12 and mill use exceeding production by 5.3 million bales.
Figure 3
What Our Apparel Index Is Showing
To gain access to Turnleaf’s proprietary Apparel indicies for development markets and the rest of this article, visit our latest Substack post, here.
Research Archive
Macroeconomic Insights: Strait of Hormuz and the Inflation Shock Markets Are Repricing
The US-Israel strike on Iran has pushed Middle East risk back to the center of global pricing. Crude has firmed into the low 70s while European gas prices spiked, and gold has...
Macroeconomic Insights: Trump’s Tariff War – The Sequel
On Feb 20, 2026, the Supreme Court ruled 6–3 (Learning Resources, Inc. v. Trump) that the International Emergency Economic Powers Act (IEEPA) does not authorize the U.S....
Macroeconomic Insights: Gold’s New Inflation Playbook
Gold has stopped trading as a clean derivative of US real yields and now reflects a broader external pricing regime. Since 2022, the real-yield anchor has weakened, gold has...
TradeTech FX USA 2026
Over recent years, the finance community in Miami has grown, given that a number of hedge funds have opened up large offices there. Every February, the FX community from New...
Macroeconomic Insights: India CPI – Basket Reweighting Explained
India's National Statistical Office launched a new Consumer Price Index series on February 12, 2026, shifting the base year from 2012 to 2024 and overhauling the basket...
Macroeconomic Insights: UK CPI — Assessing the Renters’ Rights Act 2025
Executive Summary The Renters' Rights Act received Royal Assent on 27 October 2025. Council investigatory powers commenced on 27 December 2025, and the main rent-setting...
Macroeconomic Insights: South Africa CPI – When Currency Strength Meets Energy Vulnerability
After trending downward through most of 2025 alongside rand appreciation and falling oil prices, Turnleaf’s 12 month inflation forecast for South Africa is now pointing at rising...
Macroeconomic Insights: Colombia CPI: The Minimum Wage Shock
Colombia’s 12-month inflation outlook for 2026 has been revised higher. We now expect inflation to hit up to 6.7%YoY by the end of the year (Figure 1). This is a clear break from...
Macroeconomic Insights: Expect the Unexpected
Mark Carney at Davos, January 20, 2026 "For decades, countries like Canada prospered under what we called the rules-based international order. We joined its institutions, we...
Macroeconomic Insights: Eurozone CPI — “Sweater Weather” Is Repricing Energy Risk
Energy markets have moved back to the foreground as a near-term driver of Eurozone headline inflation. Colder January temperatures lifted heating and power demand into a winter...
AI coding is like making a burger with sugar
Have you ever had a burger, and then noticed something is kind of off. You’re hunting for the reason. Then it’s immediately obvious: they put sugar instead of salt. Ok, this has...
Macroeconomic Insights: Turkey CPI – Inflation Pinned in Gold
Gold jewelry remains a common wedding gift in Turkey, reflecting a cultural practice where households preserve wealth through physical gold rather than financial assets. This...
Macroeconomic Insights: US CPI – November’s Weakness is Not All December’s Gain
The October–November 2025 CPI sequence contained meaningful measurement distortions linked to the federal government shutdown. BLS has since confirmed that most CPI operations...
Macroeconomic Insights: Colombia CPI – Minimum Wage Shock Meets Fiscal Emergency
Turnleaf expects Colombia CPI to accelerate towards 6% YoY starting January 2026 following a 23.7% minimum wage increase that took effect on January 1—a significant upward...
Inflation Outlook 2026: New Year, New Inflation Regime?
Over the past year, global disinflation efforts have been complicated by escalating trade tensions that slowed global growth, geopolitical conflicts in the Middle East and...